$$ SHOW ME THE MONEY!!! $$
How much can a loan assumption save you? The savings can be staggering!
Same Home - HUGE Savings!
- Significant reduction in the monthly payment vs getting a new 30 YR mortgage at the prevailing rate
- Staggering savings over the life of the loan! Not only did the buyer save on each monthly payment, the assumable loan only had 314 payments remaining vs. 360 with a new mortgage!
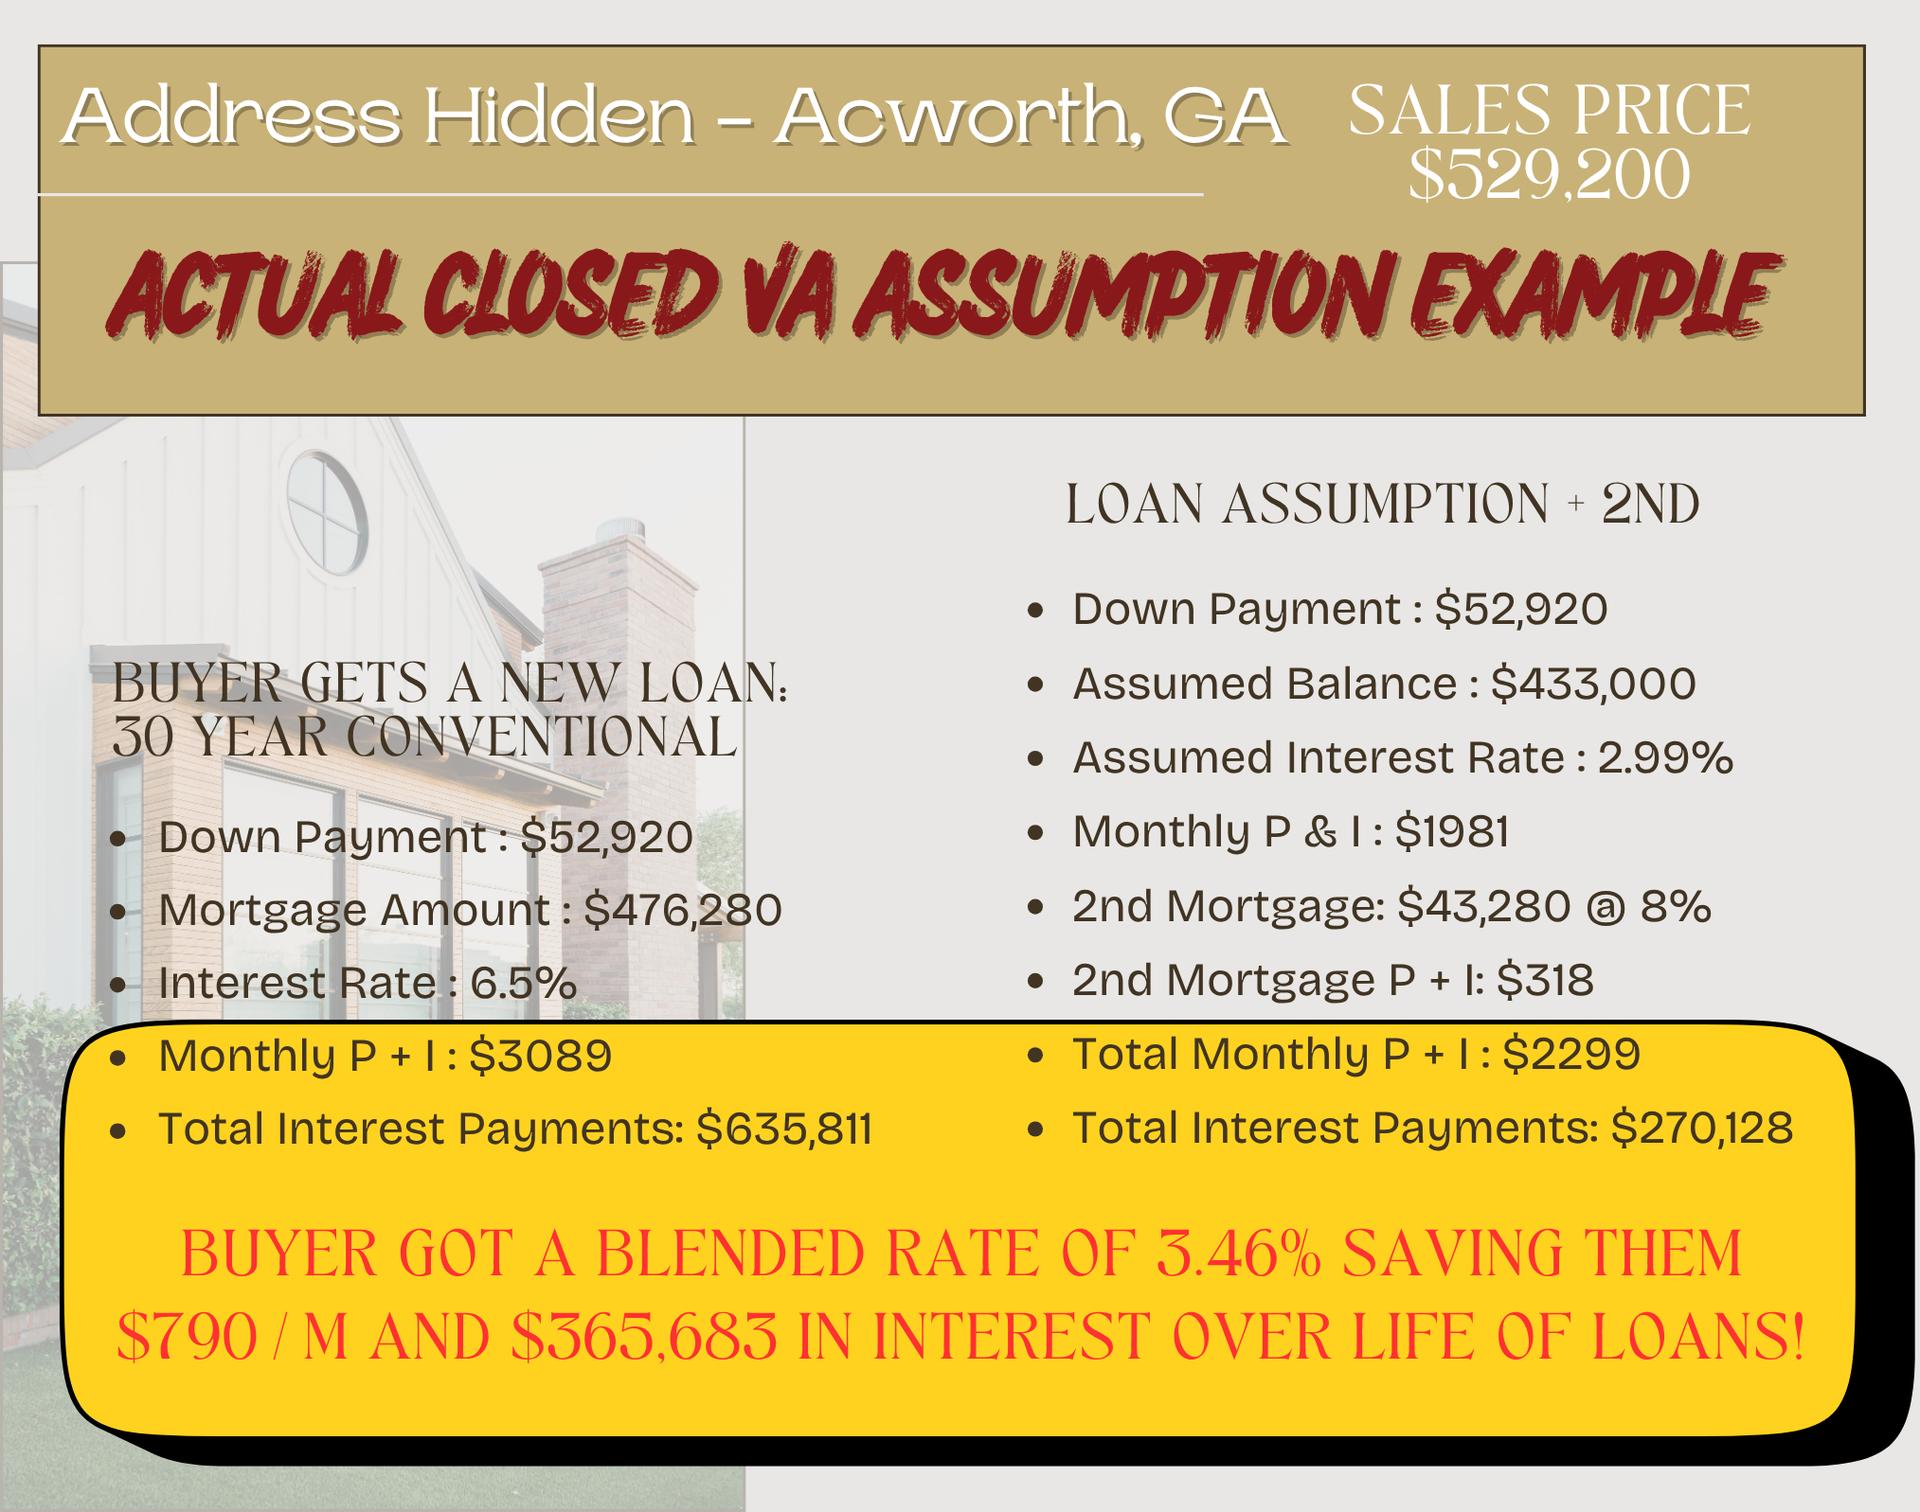
** In both scenarios, the buyer put 10% down. For the loan assumption scenario, the buyer assumed the seller's loan balance and used a purchase money 2nd mortgage to cover the remainder of the equity gap. The 2nd mortgage had a 30 year amortization (not interest only). The blended interest rate is a weighted average factoring in the loan amount and interest rates of the assumed mortgage and the purchase money 2nd mortgage. The larger the down payment, the better the blended interest rate. Purchase money 2nd mortgages are available to cover both FHA and VA equity gaps with as little as 5% of the purchase price as a down payment.
Buy More - Pay Less!
Have you been approved for a loan amount but have not been able to find the right home in your price point? See how an assumable loan can make a significant difference in the price you can afford. Consider the following scenario:
- Your lender has approved you for a 30 year conventional mortgage with a purchase price of $425,000. With a 6.5% interest rate (Mortgage Insurance built into the rate), you expect to have a Principle + Interest Payment of about $2552 putting 5% down. After looking at everything on the market, you have not been able to find the home you want in the location you want. Your agent suggests you need to increase your price point but you either can't afford or don't want to spend more each month on your mortgage payment. What if there was another option?
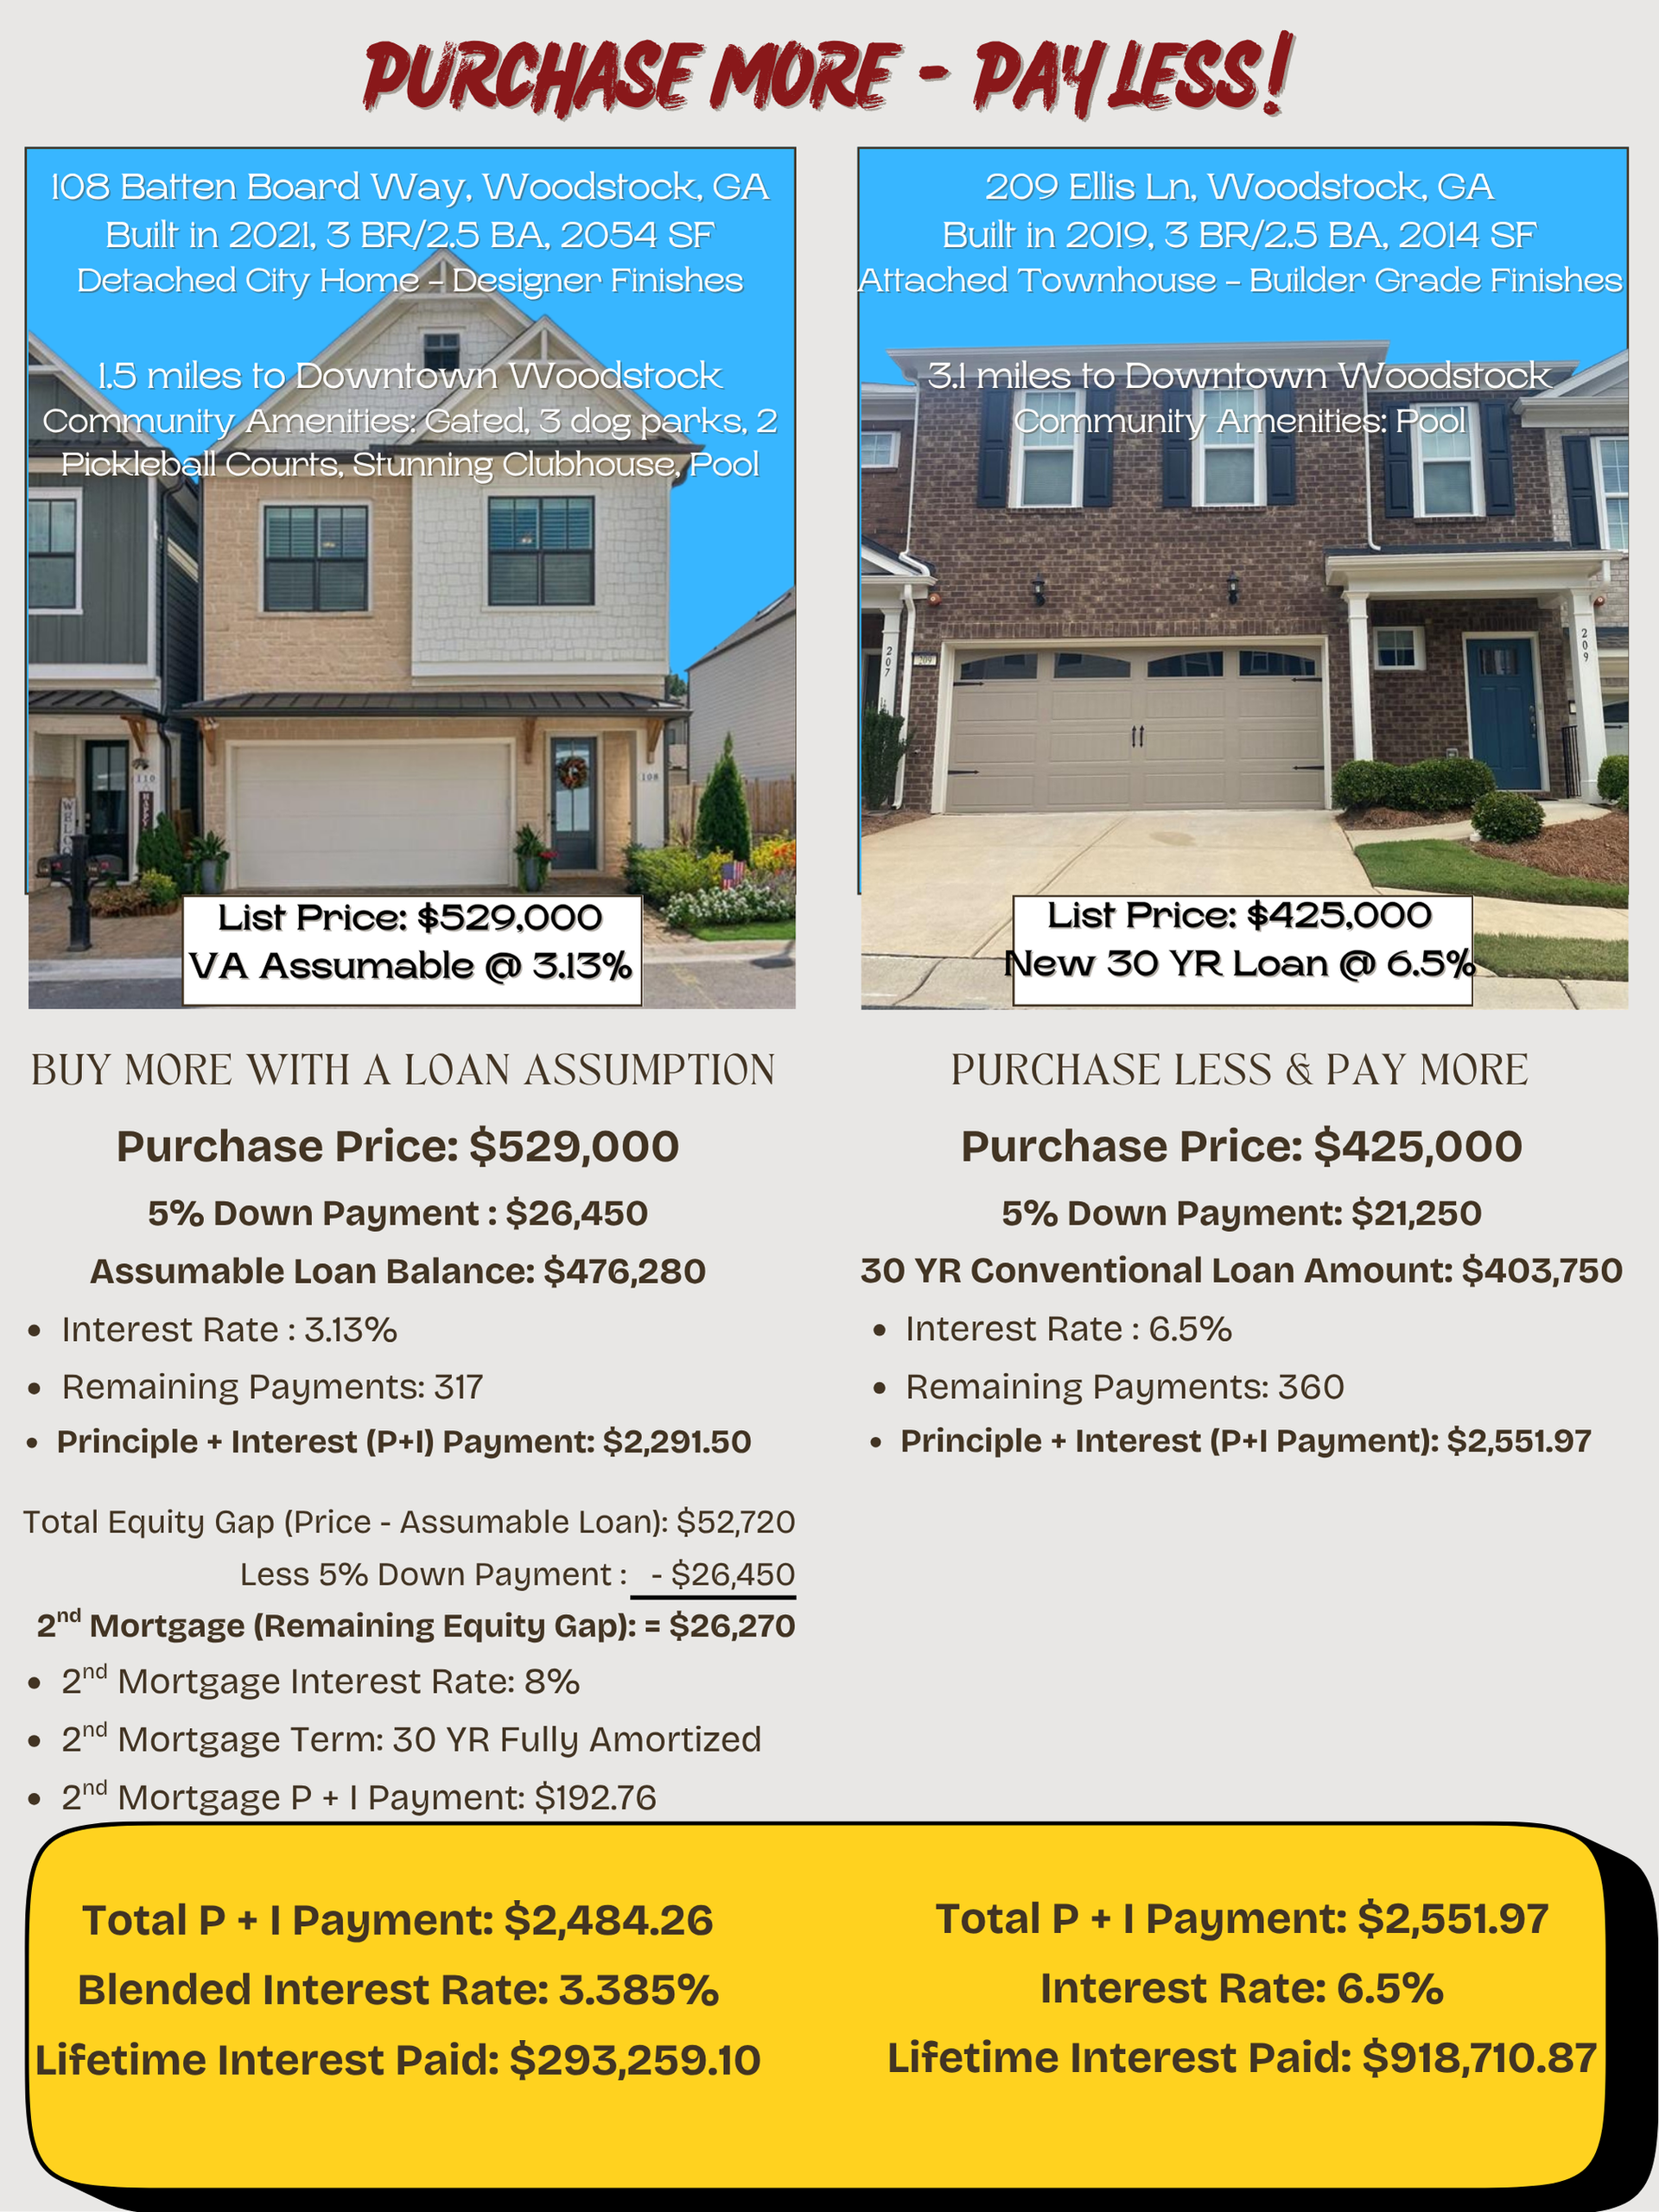
** In both scenarios, the buyer put 5% down of the purchase price. For the loan assumption scenario, the buyer assumed the seller's loan balance and used a purchase money 2nd mortgage to cover the remainder of the equity gap. The 2nd mortgage had a 30 year amortization (not interest only). The blended interest rate is a weighted average factoring in the loan amount and interest rates of the assumed mortgage and the purchase money 2nd mortgage. The larger the down payment, the better the blended interest rate. Purchase money 2nd mortgages are available to cover both FHA and VA equity gaps with as little as 5% of the purchase price as a down payment.
Have Questions?
We're here to help!
 ©2026 Georgia Multiple Listing Service All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may
 Listings identified with the FMLS IDX logo come from FMLS and are held by brokerage firms other than the owner of this website. The listing brokerage is identified in any listing details. Information is deemed reliable but is not guaranteed. If you believe any FMLS listing contains material that infringes your copyrighted work please
 Northeast Georgia Board of REALTORS® All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be
